You give your time to a non-profit in Central New York because the mission matters. Insurance may not feel like part of that mission. Without an insurance background, it’s hard to know which policies fit your risks. The worry isn’t just a lawsuit. It’s buying a policy that leaves a gap you didn’t see.
At the Horan insurance agency, we work with multiple carriers across Central New York. That gives us a view of how coverage options compare for non-profits like yours.
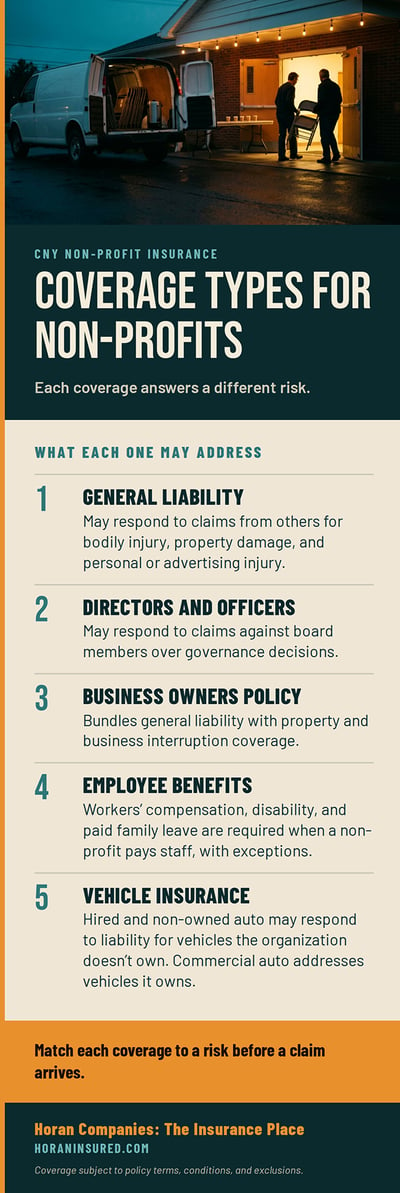
This article explains what general liability, directors and officers, business owners, employee benefit, and auto coverages may address for a non-profit, and where volunteers fit in.
Why Do Non-Profits Carry Insurance?
Non-profit status doesn’t exempt an organization from liability claims, so many non-profits carry insurance to address that exposure. A guest who gets hurt at an event can bring a claim whether or not the host is a charity.
Consider a hypothetical Liverpool non-profit that has hosted community events for a decade without a policy. At a board meeting, a new member asks who would respond if a guest were hurt at the next fundraiser. The room goes quiet.
Without coverage, the organization could face defense costs and any judgment from its own funds. That could strain donations and volunteer support.
Does General Liability Insurance Address a Non-Profit’s Events and Operations?
General liability insurance could provide coverage for claims that a non-profit’s operations caused bodily injury, property damage, or personal and advertising injury to someone else. A policy responds subject to its terms, conditions, and exclusions. Our guide to general liability insurance in Central New York covers the basics.
Imagine volunteers hanging banners at a street fair. One banner isn’t secured well, a gust tears it loose, and it lands on a passing car. The driver swerves and hits another vehicle. A general liability policy may respond to the resulting damages and legal fees, depending on its wording.
General liability addresses claims from other people. It doesn’t address injuries to the organization’s own employees or damage to its own property.
Can General Liability Insurance Address Online Claims?
It may, for certain personal and advertising injury claims, depending on the policy wording. Allegations such as defamation or slander can fall into that category.
Suppose someone alleges that a non-profit’s social media post defamed them. A general liability policy may respond to the legal defense costs and any damages, subject to its exclusions. Data breaches and cyberattacks often call for separate coverage. Our article on cyber liability coverage for Central New York businesses explains that coverage.
 What Does Directors and Officers Insurance Do for a Non-Profit Board?
Directors and officers insurance may respond to claims that board members or officers made wrongful decisions in their governance roles, including legal defense costs, subject to policy terms. Even diligent board members can face accusations of mismanagement or oversight. Claims could involve allegations such as these:
- Mismanaged funds: If board members face accusations of poor investment decisions or misuse of funds, the policy may respond to the associated legal costs.
- Regulatory non-compliance: If the non-profit fails to meet regulatory standards, the policy may respond to legal expenses tied to that failure.
- Failure to perform duties: If board members face lawsuits for not fulfilling their legal or fiduciary duties, the policy may help with legal defense costs.
A board member may feel more comfortable serving when the organization carries this coverage. That may help a non-profit recruit and retain board members.
Learn more about directors and officers insurance.
How Does a Business Owners Policy Differ From General Liability Insurance?
And business owners policy bundles general liability insurance with property insurance and often business interruption insurance. General liability insurance addresses liability claims by itself.
A business owners policy may fit a non-profit that owns or manages physical assets, such as office space, equipment, or inventory. It may respond to liability claims, damage to covered property, and lost income after a covered event. Carriers set their own eligibility rules, so availability varies.
Does a Non-Profit Have to Carry Workers’ Compensation, Disability, and Paid Family Leave?
A New York non-profit that pays people for their services must carry workers’ compensation, disability, and paid family leave coverage for those employees, with some exceptions. Workers’ Compensation Law Sections 2 and 3 set the workers’ compensation requirement. Section 202 sets the employment threshold for disability and paid family leave.
These three coverages each do something different:
- Workers’ compensation may provide benefits to employees, such as program staff or maintenance workers, who suffer job-related injuries and illnesses.
- Paid family leave may provide paid time off to bond with a new child or care for a family member with a serious health condition. Employers add it to a disability benefits policy, and it is separate from short-term disability.
- Short-term disability may provide income replacement for employees who can’t work because of a non-work-related illness or injury.
Exceptions exist. Clergy whose work is limited to religious duties, some teaching and non-manual roles at charitable, religious, and educational non-profits, and compensated executive officers at those organizations who do no manual labor may fall outside the workers’ compensation requirement. The Workers’ Compensation Board’s coverage guidance lists them.
A non-profit that pays no one isn’t required to carry these coverages. The Board counts stipends, room and board, and other perks with monetary value as compensation. Money that covers a volunteer’s expenses, and nothing more, doesn’t count.
Under the Board’s guidance, unpaid volunteers doing charitable work for a non-profit aren’t employees, so the requirement doesn’t reach them. Our article on volunteer accident insurance for CNY non-profits explains what may apply instead.
Learn more about workers compensation and short-term disability/paid family leave.

How Do Hired and Non-Owned Auto and Commercial Auto Insurance Work for Non-Profits?
Hired and non-owned auto insurance may provide liability coverage when someone sues a non-profit over an accident involving a vehicle it doesn’t own, such as a volunteer’s car or a rental. Commercial auto insurance addresses vehicles the non-profit owns.
Consider a volunteer driving to a charity function. In the event of an accident, the injured party’s claim for compensation may not consider the organization’s non-profit status. Without coverage, the organization’s finances may be exposed to such claims.
Hired and non-owned auto coverage addresses the organization’s liability. It doesn’t pay for damage to a volunteer’s own car, which the volunteer’s personal auto policy may address. Depending on the carrier, it may come with a business owners policy or as an endorsement. Our article on hired and non-owned auto insurance for CNY businesses explains where gaps can appear.
For vehicles the non-profit owns, commercial auto insurance may respond to legal bills, medical expenses, and property damage, depending on the coverages selected. With comprehensive coverage added, it may also respond to damage from non-collision events such as fire, theft, animal strikes, weather, or vandalism. Our guide to commercial auto insurance in Central New York covers the options.
Matching Each Coverage to a Non-Profit Risk Before a Claim Arrives
You already give your time and energy to your community. Adding insurance decisions to that load isn’t easy, since each policy answers a different question.
We covered how general liability, directors and officers, business owners, employee benefit, and auto coverages may respond to different risks. Sorting out which ones apply can give your board and staff composure and stability. Overlooking a gap could mean a claim arrives before the conversation does.
As an independent agency working with multiple carriers across Central New York, the Horan insurance agency would like to be a resource as you compare options. We can walk through how your current policies may respond and where a gap may remain.
Click the Get a Quote button below to start that conversation.
This article provides general information about insurance for non-profit organizations in New York. Coverage is subject to policy terms, conditions, and exclusions, and requirements change over time. Please consult your licensed agent about your specific circumstances.

Topics: