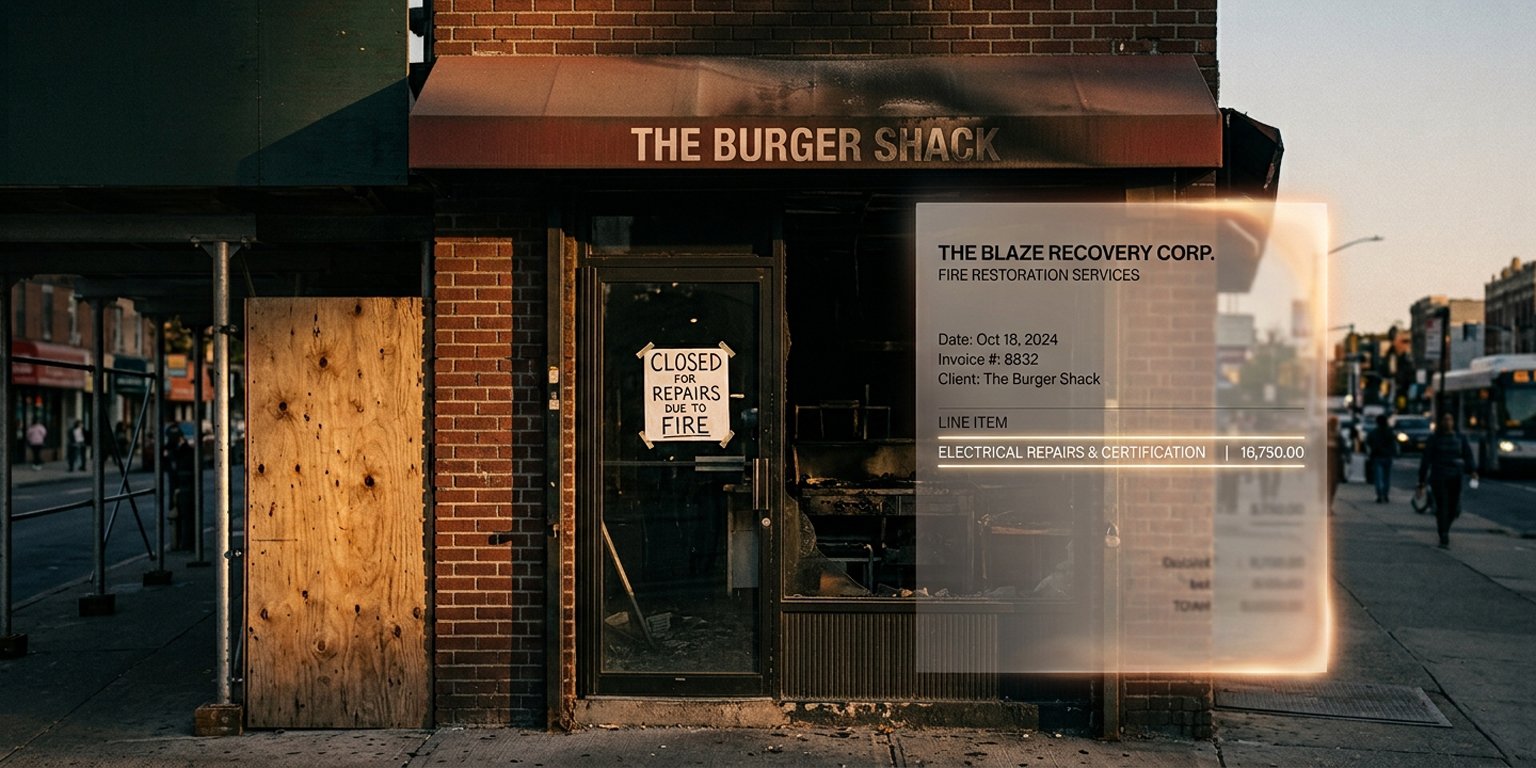
A covered loss closes your franchise location, and business interruption coverage begins replacing the income you're not earning.
Without a background in how that limit gets built, it's easy to sign off on a number without knowing whether it covers what you owe. The real worry isn't the closure itself — it's discovering the limit wasn't built for your obligations.
At the Horan insurance agency, we work with multiple carriers across Central New York, giving us a view of how a business income limit gets calculated and what it's meant to include.
This article covers how business interruption coverage separates fixed obligations from variable ones, where a franchise fee typically falls, and what that means for the limit you select.
Does Business Interruption Coverage Include a Franchise Fee?
Business interruption coverage — commonly written on the standard ISO Business Income form, filed as CP 00 30 — is generally built to include fixed obligations continuing whether or not your location is open, alongside the income it replaces. A monthly franchise fee that doesn't change with sales functions like other fixed costs, such as rent or a loan payment.
Whether that fee is fully reflected in a claim payout can depend on how the limit was calculated, not just the policy's design. A limit built from a general profit-and-loss estimate, rather than an itemized list of continuing obligations, can fold a fixed fee like a franchise royalty into a broader number without calling it out on its own.
Why a Percentage-of-Sales Royalty Behaves Differently Than a Flat Fee
A royalty calculated as a percentage of sales typically shrinks toward zero along with the revenue it's based on, since there's little left to calculate a percentage of during a closure. That differs from a flat monthly fee or a set minimum royalty, which continues at the same amount regardless of how much the location sold that month.
Many franchise agreements combine both structures — a flat baseline fee plus a percentage above a set sales threshold. Reading your own agreement's fee structure is the only way to know which portion continues during a closure and which portion adjusts down with lost sales.
Building a Coverage Limit That Accounts for Your Franchise Fee
Building a coverage limit that accounts for a franchise fee means pulling the fixed amount from the franchise agreement, rather than estimating it from financial statements. The agreement states the number; the financials only show what was paid, which can blend the fee into other overhead. This matters most at renewal, when a fee changes before the financials catch up.
Obligations worth itemizing separately when building or reviewing a business income limit include:
- The fixed or minimum portion of a franchise royalty, apart from any percentage-of-sales portion
- Any fixed marketing fund contribution required by the franchise agreement
- Rent, loan payments, and other fixed costs that continue regardless of whether the location is open
 Reviewing This Alongside What Your Franchise Agreement Requires
Confirming a policy meets a franchise agreement's minimum insurance requirements and confirming the coverage limit carries the agreement's fixed fees are two separate checks — a franchisee can complete the first without ever doing the second.
Consider a hypothetical: a franchisee running a quick-service restaurant in a town like Clay or Cicero carries a franchise agreement with a flat monthly fee plus a percentage-of-sales royalty above a set threshold. A covered fire closes the location for several months, and the flat fee keeps coming due the entire time.
Reviewing what a franchise agreement's insurance section requires before you sign covers the first check. This article covers the second — and a franchisee benefits from treating them as two separate reviews rather than assuming one covers the other.
Before finalizing or renewing business income coverage, it helps to:
- Pull the franchise agreement's fee structure and separate the fixed portion from the percentage-of-sales portion
- Compare that fixed amount against how your current coverage limit was calculated
- Ask a licensed agent whether the fixed fee is itemized in the limit or folded into a general estimate
- Revisit the limit whenever the agreement's fee structure changes at renewal
We covered how business interruption coverage separates fixed obligations from variable ones, where a franchise fee typically falls between the two, and what that means for building a coverage limit that actually carries it.
Reviewing your limit against your agreement's fee structure before a loss means a closure doesn't also become the moment you discover the limit was never built to include what you still owe. Skip that review, and the gap surfaces only once a claim is already being calculated, when there's no way to adjust the limit that applies to it.
As an independent agency working with multiple carriers, the Horan insurance agency can walk through how your business income limit was calculated and whether it accounts for your franchise agreement's fixed obligations, giving you composure and stability heading into a closure rather than uncertainty about what your coverage actually carries.
Click the Get a Quote button below to review your business interruption coverage against your franchise agreement's fee structure.

Topics: